WDC

#ShortStrangles #ReverseRolling – Screwed the pooch on my roll to inverted by being impatient so reverse rolling calls into low risk put spreads for a credit. Going directional since it’s one I wouldn’t mind trading around for awhile. Went inverted on the original strangle WAY too early.

Rolled WDC DEC 29 2017 79.5 Calls to JAN 19 2018 85.0/80.0 Bull Put Spreads @ .43 credit.

This is another one of those where it doesn’t really matter to me how low it goes. With 3.80 of accumulated premium on the 5 wide spread the worse case scenario is owning the stock at a basis only 1.20 above where it happens to be at expiration…(as long as I book the long put gains late on expiration day and let the shorts get exercised)

Still holding short 82.5 puts from original strangle….

BIDU

#SyntheticStock #IRA – Weekly sale not quite going to expire today…

Rolled BIDU DEC 8 2017 235.0 Calls to DEC 15 2017 240.0 Calls @ .40 credit (4.85 accumulated premium on this one)

SVXY

#ShortPuts – Bottom of the Jan ladder starting to get taken out…

Bought to Close SVXY JAN 19 2018 35.0 Puts @ .25 (sold for 1.28)

TOS range bars

Thank you @hcgdavis for pointing these out! Even without day trading I think these are going to help a lot with entries. Had I been watching them could’ve easily waited a little before selling that SPX put. When red turns green sell it!

BTW…just swing trading the second bar of a color change on a slow mover like BIDU since Dec 1st would’ve made (you do the math) on 200 shares. I know…woulda coulda shoulda but something I’ll be watching…especially for catching some reversals on XIV and SVXY on those crazy days.

SPX

#RocketManHedge – Booking and selling…this sale completes the covering of max loss on the hedge with another month to run. After this I’ll start giving it a little more downside room. Make a little but keep a strong hedge though Jan expiration.

Skipping Friday since it only trades thru Thursday close. Selling the following Monday instead.

Bought to Close SPX DEC 8 2017 2625.0 Put @ .15 (sold for 7.10)

Sold SPX DEC 18 2017 2625.0 Put @ 5.40

ADSK

#ShortStrangles – An #Earnings play that turned into strangles. Oversold the call side and now seeing a nice bounce. Booking this week’s.

Bought to Close ADSK DEC 8 2017 111.0 Calls @ .27 (sold for .85)

AAOI

#ShortStrangles – If there’s one thing I’ve learned this year (it’s lead to my 3 biggest losers of 2017) is to not chase short puts up on a rising stock too aggressively. A massive whipsaw can ensue leading to chaos. OK…maybe that’s a little dramatic but…making a big adjustment, limiting downside risk, and settling in for the long haul of selling weeklies to get back to at least even.

Rolled AAOI JAN 19 2018 80.0 Puts to JAN 18 2019 80.0 Puts @ 5.17 credit
Bought AAOI JAN 18 2019 20.0 Puts @ 3.20

Pocketing nearly 2 bucks on the roll/protection. Now…I’m limited to a 60 point loss and I’m free to sell non-aggressive weeklies without worry of max loss (bankruptcy?…don’t trust these types of places)

So far I’ve accumulated 25.40 in premium to this point so still 34.60 in the hole if it goes to zero (less than that if it recovers over the next year). Using the 34.60 as max loss and 58 weeks to I’ll be looking to sell about 60 cents a week. It’s a long haul but worth it to turn around a loser if I can.

BTW…TDA margin is 975 on 3 contracts to hold this trade so not a big deal..

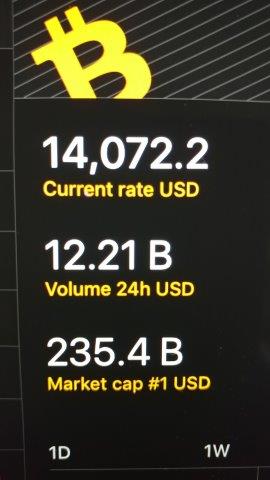
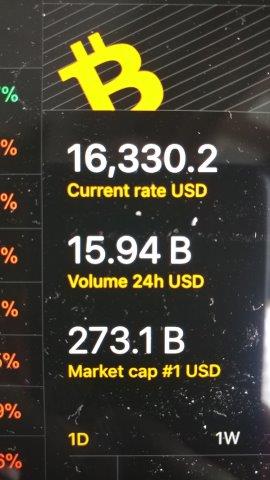
BTC (Bitcoin)

#OffTopic – And I thought SVXY was strong today…how’s that for a little 12 hour run?

BTC (1)

BTC (2)

AVGO

$ShortPuts – Selling the put side on the little dip and looking to leg into the #ShortStrangles . Fairly short time frame with a holiday mixed in and could be a little residual IV left over from earnings also.

Sold AVGO DEC 29 2017 250.0 Put @ 1.90

AVGO

#Earnings – Taking advantage of the little pullback to book the winner. I might be early…or not 🙂

Bought to Close AVGO DEC 8 2017 255.0/265.0/275.0 Iron Fly @ 5.69 (sold for 7.82)

AVGO earnings

#Earnings – I’ve got the AZO winner in the bank so rolling the dice on all my RH profits with a defined risk iron fly 10 wide with an expected move of 11.75. Risk about 2 to make 8. Leaning slightly bullish with the stock sitting at support.

Sold AVGO DEC 8 2017 255.0/265.0/275.0 Iron Fly @ 7.82

BTC…where does this end?

https://www.cnbc.com/2017/12/06/bitcoin-tops-13000-surging-1000-in-less-than-24-hours.html

NVDA

#SyntheticStock -Been waiting for some sort of a pullback to get in this long term Whiz style (although he prefers the #LongCallDiagonals for some reason).

Sold NVDA JAN 17 2020 190.0 Puts @ 37.75
Bought NVDA JAN 17 2020 190.0 Calls @ 43.70

Adding tight disaster puts. If it implodes I’ll roll this down and re-invest the profits back into more longs.

Bought to Open NVDA JAN 17 2020 185.0 Puts @ 35.05

This gives a net debit of 41.00 for the Jan 2020 position. Add the 5 point max downside and get a max loss possibility of 46.00. Based on that, and the 110 weeks remaining in the trade I only need to average about 42 cents per week in sales to cover the absolute worst case scenario. And…NVDA has great weekly premium.

Sneaking my first sale in this week to cover the small DIS loss:

Sold NVDA DEC 8 2017 195.0 Calls @ .48

HSIC

#ShortPuts #IRA – Already dealing with UAA so keeping this one on a short leash with the AMZN rumor today. One contract small loss and moving on. I’d re-post the chicken if it wasn’t so big!

Bought to Close HSIC Apr 20 2018 60.0 Put @ 1.95 (sold for 1.75)

#fallingknife

Trading DIS for NVDA

#SyntheticStock – As @1strangealien and I were discussing down below I’ve bailed on DIS for a small loss and established a new position in NVDA (one of my favorites). Decent liquidity and great premium for weekly selling against the long term position.

DIS details: (I’ll post seperately with the NVDA details)

Sold to Close Jan 2020 100 strike synthetic stock @ 6.90
Sold to Close Jan 2020 90 strike disaster puts @ 5.50
Bought to Close Jun 2018 105 calls @ 6.70

Net credit of 5.70 plus front month premium received of .40 so 6.10 total. Cost to enter the trade was 6.63 so final numbers work out to a loss of .53. I’ll roll that into my NVDA cost and have it made up this week. LOL Hate a loser but really wanted a crack at NVDA so happy to close it.

ADSK

#ShortStrangles – Getting a jump on next week in case the 200ma doesn’t hold. Selling weeklies to lower basis in Jan 120 puts..

Sold ADSK DEC 15 2017 109.0 Calls @ 1.21

EWW

#ShortStrangles – Booking a little and a delta adjustment. Still slightly long…

Bought to Close EWW DEC 15 2017 51.0 Calls @ .19 (sold for 2.05)

Sold EWW DEC 22 2017 49.0 Calls @ 1.15

Selling weeklies against Jan 54 puts

LRCX

#ShortStrangles – First time in this one. Staying small…

Sold LRCX JAN 12 2018 160.0/200.0 Strangle @ 4.30

SWKS

#ShortStrangles – Rolling down to slightly inverted…

Rolled SWKS DEC 29 2017 118.0 Calls to SWKS DEC 29 2017 100.0 Calls @ .90 credit

Position is now 103/100 inverted strangles @ 2.73

RH

#Earnings – No interest in even taking a chance of getting any stock. Kind of a weak open so bailing with good profit. Thanks Jeff!

Bought to Close RH DEC 8 2017 90.0/120.0 Strangles @ 1.05 (sold for 2.40)

AAL “insider trading” ?

Not sure if anyone has seen our headlines lately. Long story short…technical glitch allowed pilots system wide to drop trips in December that normally wouldn’t be allowed. Now we are looking at tons of open flying that nobody seems interested in even after the company offer of double time to pick them up. I believe the company is downplaying the severity of this to preserve holiday bookings…

https://www.cnbc.com/2017/11/29/thousands-of-american-airlines-flights-dont-have-scheduled-pilots-union.html

https://www.npr.org/sections/thetwo-way/2017/12/01/567903691/american-and-pilots-work-out-deal-to-save-holiday-flights

https://www.usatoday.com/story/travel/flights/todayinthesky/2017/12/05/pilot-scheduling-mix-up-could-cost-american-10-million-analyst-estimates/922432001/

I could be totally wrong too. I hope so since I’m on call over Christmas and New Year’s…LOL But…if we get a little news story about how maybe everything isn’t as it may seem, I’m going to take a low risk shot at some downside using the @vxxkelly butterfly hedge. Tiny risk for possibly decent reward. I don’t see an implosion but possibly a small pullback so love the idea of trying to do it for a credit.

Have to double check the numbers when the market is open but right now the 49/47/45 or 48/46/44 looks like pretty good risk/reward.

FWIW…

RH

#Earnings – Rode “Jeffretariat” to a pole to pole winner at the AZO derby so saddling him up again for a run in the RH stakes. Can he do it back to back?

Sold RH DEC 8 2017 90.0/120.0 Strangles @ 2.40

EWZ

#ShortStrangles – Been working this one for awhile as a #PerpetualRollingStrangles trade and had it narrowed down to a Dec monthly short straddle. The price is at the straddle strike today so taking the opportunity to book it for decent profit and re-sell and re-center.

Bought to Close EWZ DEC 15 2017 40.0 Straddles @ 1.93 (sold for 2.72)

Sold EWZ JAN 5 2018 37.0/43.0 Strangles @ .82

TLT

#PerpetualRollingStrangles – This is almost a freebie since the sales are near my inverted strikes. Selling 50 ma and above recent highs…

Sold TLT JAN 12 2018 125.0/130.0 Strangles @ 1.35

GLD

#SyntheticStock – Selling next week early. Order in to close this week at a penny. Very conservative on these weekly sales now. This particular trade only needs about 12 cents a week to cover max loss. Struggling so far but….synthetic short stock position on NUGT working nicely!

Sold GLD DEC 15 2017 122.0 Calls @ .23

AZO

#Earnings – Margin hog so taking off for a nice winner. Frees up my earnings firepower for AVGO tomorrow…

Bought to Close AZO DEC 8 2017 625.0/775.0 Strangle @ .91 (sold for 6.20)

AAPL

#SyntheticStock – Rolling front month back out to 45 days and just before earnings. Could possibly get one more nice roll into earnings week…

Rolled AAPL DEC 22 2017 162.5 Calls to JAN 19 2018 165.0 Calls @ .35 debit.

Debit roll but picking up another 2.15 of upside. Front month premium received now reduced to 2.60

NVDA

#ShortPuts #IRA – Adding another one….

Sold NVDA MAR 16 2018 150.0 Put @ 3.69

REGN

#CoveredCalls – Showing some signs of life. Pounded it all the way down so trying to get out of the way for the rise from the ashes. Easing this up for now…

Rolled REGN DEC 15 2017 380.0 Call to DEC 29 2017 385.0 Call @ .20 credit

DIS

#SyntheticStock – Rolling up and out for a small debit but picking up 3.70 more upside. DIS has lousy strikes for rolling…5 wide in the monthlies. This is another bigly profit blocked by front month calls. From now on I’m changing my attitude about these. Instead of going for aggressive max premium on the weekly sales I’m going to be much more conservative.

When I set these trades up it usually works out where only very small weekly sales are needed to cover any max potential loss since they are all hedged. Let’s say 15 cents is all that’s required each week. I’ll limit myself to 30 cents on the sales which would still be a double long term but would also leave plenty of upside room for these runaway trains…

Rolled DIS DEC 29 2017 100.0 Calls to JUN 15 2018 105.0 Calls @ 1.30 debit.

NVDA

#ShortStrangles – Rolling call side down a little for additional premium…

Rolled NVDA DEC 15 2017 210.0 Call to DEC 15 2017 200.0 Call @ 1.50 credit.

Position is now Dec monthly 200 Straddle @ 7.75

SVXY butterfly experiment

I’m not much of a regular old butterfly guy (other than iron butterflies for earnings) so maybe I did something wrong. The SVXY put butterfly that @vxxkelly and I were discussing as a #Hedge didn’t do much during the selloff Friday. I monitored it as SVXY dropped all the way down and then all the way back up and the thing was never profitable at all. Was it because it was out in Jan? Do these types of trades only work on much shorter time frames? Did I (quite possibly) screw something up?

Here was the trade:

SVXY JAN 19 2018 110.0/105.0/97.5 Put Butterfly @ .22 credit

Bought 5 110 puts
Sold 10 105 puts
Bought 5 97.5 puts

WYNN

#ShortStrangles – Another roll against DITM calls. Nice consistent premium every week.

Rolled WYNN DEC 1 2017 160.0 Puts to DEC 8 2017 160.0 Puts @ 1.81 credit

UVXY

#IRA #VXXGame – Replaced a few others that were closed earlier this week…

Sold UVXY JUN 15 2018 30.0/45.0 Bear Call Spreads @ 1.20

SVXY

#ShortPuts #VXXGame #IRA – Out most of the morning but luckily caught some of the dip. Was able to re-sell a few that were closed earlier this week. 🙂

Sold SVXY DEC 15 2017 90.0 Put @ 2.46
Sold SVXY JAN 19 2018 75.0 Put @ 2.80
Sold SVXY MAR 16 2018 60.0 Put @ 3.40

ADSK

#ShortStrangles – Replacing today’s expiration…

Sold ADSK DEC 8 2017 111.0 Calls @ .85

SVXY put butterfly

#Hedge – Thanks to @vxxkelly …giving this a try.

Bought SVXY JAN 19 2018 110.0/105.0/97.5 Put Butterfly @ .22 credit

SPX

#RocketManHedge – This has been kind of a fun/interesting trade/experiment. Originally put on synthetic short stock with a disaster call for 45.0 debit with max loss of 50.0 out in Jan 2018 monthly. Had enough time to sell about 4 points a week to cover max loss and still constantly carry about a 40 point downside hedge.

With the rally I’ve been selling much more aggressively and have already recovered all but about 12 points of the max loss and still have 6 weeks to run. Looks like the hedge will still be nicely profitable even though the market has gone completely against it. I’ll still sell aggressively with the plan to roll the short put out and down if we implode.

I’m happy enough with this type of hedge I may do it in slightly bigger size next time…

Bought to Close SPX DEC 1 2017 2600.0 Put @ .25 (sold for 10.50)

Sold SPX DEC 8 2017 2625.0 Put @ 7.10

VRX

#SyntheticStock #IRA – Rolling for a small debit. Picking up another .45 of upside and keeping the expiry prior to next earnings…

Rolled VRX DEC 1 2017 15.0 Calls to JAN 12 2018 15.5 Calls @ .05 debit

EWZ

#SyntheticStock #IRA – More selling…

Bought to Close EWZ DEC 8 2017 41.0 Calls @ .12 (sold for .55)
Sold EWZ DEC 15 2017 39.5 Calls @ .72

WDC

#ShortStrangles Filled late yesterday. Easing the call side down a little for additional premium…

Rolled WDC Dec 29 2017 92.5 Calls to Dec 29 2017 85.0 Calls @ 1.05 credit

New position is now 82.5/85 Strangles @ 3.55

GLD

Big change in strategy here with much lower risk. Moving #PerpetualRollingStrangles over to a Whiz #SyntheticStock out in 2020. Same amount of margin required and taking away the naked risk of the strangles. This should also be a nice hedge in a market meltdown if everyone runs for safety.

So:

Sell to Open GLD JAN 17 2020 122.0 Puts @ 7.65
Buy to Open GLD JAN 17 2020 122.0 Calls @ 12.45

Disaster puts fairly tight:

Bought to Open GLD JAN 17 2020 120.0 Puts @ 6.85

This gives a net debit of 11.65 for the Jan 2020 position. Add the 2 point max downside and get a max loss of 13.65. I did have to close my current strangles at a small loss too:

Bought to Close GLD DEC 15 2017 125.0/118.0 Inverted Strangles @ 7.30 debit (sold for 4.20)…

That’s a loss of 3.10 but at half size of the new position so I’ll add 1.55 to my basis in the new position. This will also allow me to officially book the $6100 in realized premium that the strangles have brought in over the last year or so.

With 111 weeks remaining in the trade and a max loss of 15.20 I’ll only need to sell about 13.5 cents a week to cover the max loss worse case scenario.

So:

Sold GLD DEC 8 2017 123.5 Calls @ .28

PS…yes I could’ve just bought the LEAP calls and sold against them but I like to have the possibility of booking some profit on my hedge and maybe adding to the long position at some point.

NVDA

In an #IRA – Sold NVDA JUN 15 2018 140.0 Put @ 4.00

#jadelizard

TSLA

#ShortStrangles – Booking a small winner in one that could really get in trouble if 290 were to not hold. I’ve got no interest whatsoever in dealing with a long TSLA position at these levels.

Bought to Close TSLA DEC 29 2017 275.0/350.0 Strangle @ 4.70 (sold for 5.45)

Still holding Jun strangles…175 put against 500 and 510 calls.

ADSK

Let’s officially call this a #ShortStrangles trade now…

Rolled ADSK DEC 1 2017 120.0 Puts to JAN 19 2018 120.0 Puts @ 1.27 credit

Used half that premium received to buy a little protection at 2.5x size. May not need it it but with a little more weakness could make a small profit. Will continue selling the weekly calls…

Bought to Open ADSK JAN 19 2018 80.0 Puts @ .30

Where do we stand now? Basis in the Jan 120 puts is 116.70 so there’s work to do. It is nice knowing that if they file bankruptcy tomorrow I make 17k. Becoming a fan of these super cheap disaster puts since you never really know what’s going on in the boardroom with these “AAOI” type stocks.

🙂 🙂

SVXY

#BullPutSpreads – Closing a position that I’m very happy to be out of with a profit. This was a #ReverseRoll of some short calls that were in trouble some time ago. Tired of looking at it as well…LOL

Bought SVXY JAN 19 2018 105.0/95.0 Bull Put Spreads @ 2.40 (sold for 3.15)

These were 10 wide but still holding some that are 5 wide that wouldn’t bother me if they got in trouble since they’re a lot lower risk which were also reverse rolls… (100/95 @ 3.60)

SVXY

#ShortPuts – Trimming a little more in an #IRA. Looking for new entries now with this account at 98 percent cash.

Bought to Close SVXY DEC 15 2017 70.0 Put @ .35 (sold for 2.65)
Bought to Close SVXY JAN 19 2018 60.0 Put @ .94 (sold for 3.00)

UVXY

These are all in an #IRA so freeing up a lot of margin. They were all just bonus spreads in addition to the 2019 positions so booking them. Still short a bunch of Jan 2019 spreads. Rocketman may give another chance to get back in these.

Bought to Close UVXY MAR 16 2018 20.0/30.0 Bear Call Spreads @ .96 (sold for 1.56)
Bought to Close UVXY MAR 16 2018 40.0/50.0 Bear Call Spreads @ .32 (sold for 1.58)

Bought to Close UVXY JUN 15 2018 25.0/35.0 Bear Call Spreads @ .84 (sold for 1.21)
Bought to Close UVXY JUN 15 2018 45.0/60.0 Bear Call Spreads @ .58 (sold for 1.70)

TLT

#PerpetualRollingStrangles – Filled on this call roll late yesterday…of course today would’ve been much better. Someday one side of these will expire and I can roll the other side to something less inverted. In the meantime collecting more premium.

Rolled TLT DEC 15 2017 123.0 Calls to TLT JAN 19 2018 123.0 Calls @ .20 credit

And today:

Just going out two weeks…

Rolled TLT DEC 15 2017 127.0 Puts to DEC 29 2017 127.0 Puts @ .37 credit
Rolled TLT DEC 15 2017 130.0 Puts to DEC 29 2017 130.0 Puts @ .27 credit

NVDA

#ShortStrangles – A little adjustment for some additional premium…

Bought to Close NVDA DEC 15 2017 240.0 Call @ .05
Sold NVDA DEC 15 2017 210.0 Call @ 1.95

Position is now 200/210 strangle @ 6.22

PCLN

#ShortStrangles – Bought to Close PCLN DEC 15 2017 1550.0/1950.0 Strangle @ 1.03 (sold for 5.50)

ISRG

#ShortStrangles – Bought to Close ISRG DEC 15 2017 380.0/420.0 Strangle @ 2.15 (sold for 5.30)

ADSK earnings

#Earnings – Grabbing a little extra premium this week. Looking to roll the 120 puts out…

Bought to Close ADSK DEC 1 2017 140.0 Calls @ .01
Sold ADSK DEC 1 2017 114.0 Calls @ .90

BIDU

#SyntheticStock – Booking the weekly and selling another batch…

Bought to Close BIDU DEC 1 2017 250.0 Calls @ .25 (sold for 1.95)

Sold BIDU DEC 8 2017 245.0 Calls @ 2.91

ROKU

#ShortStrangles – This is why I’m non-directional. As soon as I take a bias one way or the other (adjusted to be long this morning) a twitter war breaks out amongst the experts and the stock sells off. I don’t want any part of it for now. Bailing with small profit.

Bought to Close ROKU DEC 15 2017 42.0 Puts @ 2.75 (sold for 3.01)

STMP

#CoveredCalls – Was still holding stock from an old earnings trade and had it covered with ITM calls for max downside protection. Chart looks like crap so I’m #ReverseRolling covered stock into a strangle. I don’t want to possibly get stuck with another falling stock and selling calls forever. Goal was to get out even once the earnings trade busted.

So:

Sold to Close covered stock @ 167.15 (that was a loss of 3.90)

To make up the loss and get back to a slight profit including commissions:

Sold STMP DEC 29 2017 160.0/195.0 Strangle @ 4.30

ROKU

#ShortStrangles – Reversing call side to puts and closing original puts…

Original trade was:

Sold ROKU DEC 15 2017 35.0/60.0 Strangles @ 3.19

I’m getting out of the way of the call side of this…

#ReverseRolled ROKU DEC 15 2017 60.0 Calls to DEC 15 2017 42.0 Puts @ .22 credit

And to stay inside my risk tolerance:

Bought to Close ROKU DEC 15 2017 35.0 Puts @ .40 debit

New position is now regular old 42 strike short puts @ 3.01

SVXY UVXY VXX

#GroundhogDay … 🙂

AAOI

These are trading just like stock at this point so just rolling for a credit to continue basis reduction. This is about the right time to roll to maintain max daily theta for something this DITM…

Rolled AAOI DEC 15 2017 80.0 Puts to JAN 19 2018 80.0 Puts @ 1.00 credit

REGN

#CoveredCalls – Guess I’ll keep selling all the way to zero… 🙂

Bought to Close REGN DEC 1 2017 392.5 Call @ .20 (sold for 4.70)

Sold REGN DEC 15 2017 380.0 Call @ 5.45

AAOI

#ShortStrangles – The grind continues…

Bought to Close AAOI DEC 1 2017 44.0 Calls @ .10 (sold for 1.15)

Sold AAOI DEC 15 2017 42.5 Calls @ 1.15

WDC

#ShortStrangles – Some sort of a downgrade so getting a nice dip here…

Sold WDC DEC 29 2017 82.5/92.5 Strangles @ 2.50

ISRG

#ShortStrangles – Currently short a Dec 8th 360/420 @ 4.30. Rolling the put side out another week and up to the 50ma for a little more credit.

Rolled ISRG DEC 8 2017 360.0 Put to DEC 15 2017 380.0 Put @ 1.00 credit

SVXY

#ShortCalls #Rolling – Rolling out and up…sticking this one above a reverse roll I did earlier to a 120/105 BuPS.

Rolled SVXY JAN 19 2018 120.0 Call to MAR 16 2018 135.0 Call @ .52 credit

TLT

#PerpetualRollingStrangles – Getting this one out of the line of fire of a possible early exercise for the dividend. Still sitting on the Dec 123 calls and 127 ,130 puts.

Rolled TLT DEC 15 2017 121.0 Calls to JAN 19 2018 121.0 Calls @ .05 credit

STMP

#CoveredCalls – Hanging on to it a couple more weeks but keeping some downside cushion. Staying ITM with the roll…

Rolled STMP NOV 24 2017 172.5 Call to DEC 8 2017 172.5 Call @ 2.54 credit

SVXY “Triple R” Repair Roll Reversal

Via special request, I’m delving into the nuts and bolts of the reverse roll repair strategy. It seems to work for any ticker but I tend to use it more often with SVXY with it’s unrelenting climb. I originally got this idea from some stuff Jeff was doing and also seeing Suz over at OMM use it as a low risk directional play on a stock.

Here we go….

My original trade was:

Sold 1 SVXY JAN 19 2018 120.0 Call @ 3.20

From the second I clicked the mouse button SVXY has pretty much gone straight up. This position is still out of the money but starting to take some heat. When the option gets near doubling the amount of premium I received I start looking at repair or adjust scenarios. Originally sold for 3.20 and currently going for 6.00 so getting close. So, what can I do? Well…lots of things:

1. Sit on my hands and hope
1a. Sit on my hands longer and hope for a black swan to fly by
2. Close for a small loss
3. Roll out and up (I like this choice too)
4. Reverse roll into 1 or more naked puts (I personally don’t add any contracts since I’m a big believer in position size control)
5. Reverse roll into a put spread (IMHO this is the safest)

**** on a side note, small position size it what allows me to make these adjustments. I’d rather have 50 single lots spread around among 50 tickers vs a single 50 lot on one ticker ****

For this example, I’m going to use choice number 5 on the list. You have to play with the numbers and decide what works best for you. I tend to look out about 3 or 4 months and try to sell something that’s around at the money. In this case, March 120/105 BuPS works but you could go more aggressive with the 130/115 for more credit. I’ll use the 120/105 in this example…

Buy to close Jan 120 call @ 6.00
Sell to open Mar 120/105 BuPS @ 6.70

Since the original call sale brought in 3.20 I’ll add that to the .70 credit for the roll for a new total premium of 3.90.

Ok…now what? How does this eventually play out on down the road? Glad you asked! Here’s some scenarios:

1. SVXY continues it’s relentless climb and our reversal goes on to be a glorious 3.90 winner.

Or: (worse case scenario which I ALWAYS look at)

2. We wake up the morning of March expiration and we’re standing in the middle of massive carnage with SVXY trading at 20 bucks. What do we do?

The spread is sitting at max loss of 11.10 (15 wide minus 3.90 received). Late in the day I’m going to sell to close the long 105 put at whatever it’s worth. I will let the short 120 put get exercised. When the dust settles my basis in the stock I received should be in the ballpark of 31 dollars. That is the current stock price plus the loss on the spread. No matter how low SVXY goes we should get the stock at a basis no worse than about 11 dollars above where it happens to be trading thanks to the spread (and if it goes to zero we’ve minimized the damage). We can then begin selling covered calls from a small hole instead of a deep crater.

Let’s say we would have chosen option 4 above in our repair choices. We could have bought the 120 call back at 6.00 and sold a March 85 put for 6.50. Net credit of 3.70 now on the 85 put. (3.20 original call sale plus .50 credit roll). Then we wake up in March with SVXY at 20 and we own stock at a basis of 81.30…ouch. A much much deeper hole to begin recovery than the 31 basis of the spread strategy.

Hopefully this fully explains my thinking on these. Any comments, critiques, or suggestions…feel free. I’m pretty thick skinned…LOL

Happy Turkey Day everyone!

#ReverseRolling

UVXY VXX synthetic short

#SyntheticShortStock – I know when something is rallying hard I like to roll the synthetic up for nice credit and to lock in some gain. What about doing the same thing on a short position. Thinking maybe rolling UVXY short down a little. Just now looking at the numbers so all a wild guess at this point…

EWZ

#SyntheticStock #IRA – Rolling front month up and out a little…picking up another 1.10 of upside.

Rolled EWZ NOV 24 2017 40.0 Calls to DEC 8 2017 41.0 Calls @ .10 credit.

SPX hedge

Hindsight is 20/20 of course…don’t need the #RocketManHedge (yet 🙂 ). I will continue selling aggressively against it to turn it into a profitable position anyway. I’ll roll this new sale down if needed but it’s bordering on a #TakeOneForTheTeam !

Bought to Close SPX NOV 24 2017 2575.0 Put @ .65 (sold for 4.95)

Sold SPX DEC 1 2017 2600.0 Put @ 10.50

WYNN

#ShortStrangles – Still pounding away at the put side against DITM Jan calls…

Bought to Close WYNN NOV 24 2017 155.0 Puts @ .20 (sold for 2.75)

Sold WYNN DEC 1 2017 160.0 Puts @ 3.47

BIDU Whiz style

#SyntheticStock -Been waiting for some sort of a pullback to get in this long term Whiz style (although he prefers the #LongCallDiagonals for some reason).

Sold BIDU JAN 17 2020 250.0 Puts @ 42.47
Bought BIDU JAN 17 2020 250.0 Calls @ 49.41

Adding a tight disaster put. If it implodes I’ll roll this down and re-invest the profits back into more longs.

Bought BIDU JAN 17 2020 240.0 Puts @ 37.17

This gives a net debit of 44.11 for the Jan 2020 position. Add the 10 point max downside and get a max loss possibility of 54.11. Based on that, and the 112 weeks remaining in the trade I only need to average about 48 cents per week in sales to cover the absolute worst case scenario. And…BIDU has great weekly premium.

So:

Sold BIDU DEC 1 2017 250.0 Calls @ 1.95

#ira

TSLA

#ShortStrangles – Lots of uncertainty and questions around this stock right now. Let’s see if it stays that way for another month…

Sold TSLA DEC 29 2017 275.0/350.0 Strangle @ 5.45

#ironcondor

REGN

#CoveredCalls – Still selling while it looks for a bottom.

Bought to Close REGN NOV 24 2017 400.0 Call @ .20 (sold for 2.60)

Sold REGN DEC 1 2017 392.5 Call @ 4.70

Lowered my cost basis on this from 470 to 421 during the drop. Might hold this long term and try to own it at an extremely low basis and make it a weekly (synthetic dividend) stock.

PANW

#Earnings – Completely missed it yesterday…and it stayed withing the expected move. Grrr!