
Sold Feb. 15, 51/55 call spread for 1.20
Recent Updates Page 287
#coveredcallcampaign GIS Sold Feb. 15,…
#coveredcallcampaign GIS SKX NKTR
GIS Sold Feb. 15, 42.50 call for .68, Tradewise recommendation
SKX rolled Jan. 18, 24 call to Feb. 8, 24 call for .85, earnings are Feb. 6
NKTR rolled Jan. 40 call to Feb. 15 for 1.60

Finally unraveling some trade adjustments…
Finally unraveling some trade adjustments over the last 14 weeks and bringing in some profits again. Have been flat for 3 months but a very nice week today 🙂
#fuzzy
EOG 110/110 with the back ratio ccs wrapped around it from the other day. With the slight pull back this morning I was able to sell 5 99 calls for 15 DTE for 1.97. What this did was lock in a no loss trade on the credit spread. Original trade was the 97/98 ccs. Back ratioed the other day. With todays trade I locked in a gain of $25 total if it closes at 98.02. Anywhere above 99 or below 97 that expands to $505. Basically inverted a butterfly but because of the gains from the back ratio now have that part of the trade risk free.
After the original post, rolled the 22 DTE 110 put out to 43 DTE for 0.45 credit. Cb now 13.96.
EXPE 120/120 125/126, 117/118 ccs and 118/120 ccs at cost basis of 9.43. Managing same as EOG. Any of the short strikes breached will delta neutral hedge (usually buy back half of the shorts).
GILD 70/70 cb 8.48. Will roll in 2-3 weeks.
MU 35/35 cb 14.80 and will roll 1-2 weeks
WDC 40/40 cb 19.11. Roll next week. This will be the longest to recover. Good thing I have a lot of time.
XBI 80/80 at 13.97 rolls in 2 weeks.
LNG 50/60 1 DTE rolled out 15 DTE for 0.48 credit. Cb 14.06
GILD 67.5/69 cb 8.90 and rolls in 2 weeks
#pietrades
LNG batch 1 61 CC should be assigned tomorrow at 57.70 cb
LNG batch 2 61 cc should be assigned at 58.53 cb.
#lizardpies
SQ should expire for full profit tomorrow. 667.50 profit on 3 contracts in 2 weeks. Finally an easy winner chicken dinner.
#spycraft
22 DTE 242.5/240.5 pcs for 0.20 credit. Small account so only 5 contracts. However, once batch 1 LNG expires this is one of the accounts I will re-dedicate to #spycraft with the mechanical management rules. Trying to double the 2 accounts in a year. Easy to keep track of since the new year.
I will be legging into an out of a lot of trades now. Anytime I can lock in a gain will do it. No guessing about what to do when short strikes are violated, they will be delta neutral hedged or shut down at a minimal loss, no questions asked. After looking at 4 years of #spycraft trades, controlling losses was the number 1 way to make this tactic profitable. The other way appears to be applying some timing by legging in and out of sides.

2dte SPX
Filled yesterday:
STO ES 1/11 2535-10 Put Spread/Binary
STO ES 1/11 2630+10 Call Spread/Binary
2.10 credit
gtc stops at 3.10 per side set.
I stopped posting until the model went back to live capital by going into the black. A loss will take it back into sim, a win will add contracts with fixed ratio sizing. Model is about even since real time testing started mid november, but just traded out of a 30% drawdown, which took a +50% improvement to accomplish.

WTW
#LongCalls #LEAPS – Another round. Getting quite a bit below my LEAPS so starting to ratio the sales a little…
Bought to Close 5 WTW JAN 18 2019 44.0 Calls @ .05 (sold for .85)
Sold 3 WTW FEB 1 2019 40.0 Calls @ .75
OLED
#ShortCalls -Nice rally today…stopped out a previous sale for over half of max profit and sold another batch too early…
Bought to Close OLED JAN 18 2019 100.0 Calls @ .50 (sold for 1.50)
Sold OLED FEB 1 2019 97.5 Calls @ 1.30

SPX 1dte IC
Legging into an SPX Jan11 IC. Sold SPX Jan11 2520/2515 pcs @.30 x6. Will sell CCS to complete IC on 5-min Tide reversal with upper study set to 0.5 and lower 0.25.
Update: Sold Jan11 2630/2635 call credit spread @.25 x6 to complete the IC based on 5-min Tide short signal.
Total credit $330 on the trade.
SPX 7dte IC ladder strategy
Sold SPX Jan18 IC 2635/2640/2480/2475 CALL/PUT @1.30 x2
#earnings #closing BBBY Yesterday sold…

Jerome can’t stay quiet
Not originally scheduled, but added to the calendar:
Federal Reserve Chairman Jerome Powell to participate in discussion at the Economic Club of Washington in Washington, DC.
Today, 12:45 ET
https://wp.me/p6Nxuc-eeY
SPX 1dte IC expired
#shortcallspreads IWM Sold Feb. 15,…
Sold Feb. 15, 150/155 call spread for .88

TQQQ
STO February 15, 50/55 bear call spread at .60 cents. I am scaling these out against my 2021 long position.
#butterfly EWW Bought Feb. 15,…
#butterfly EWW
Bought Feb. 15, 41/42/42/44 for .35
Being mechanical and following my own rules.
EOG 97/98 16 DTE credit spread was breached on the short side this morning. I delta neutral hedged it by buying back 5 of the 10 contracts at the 97 strike . Actually could have done 3 but was in a hurry. Price was 3.1 after I had sold them for 1.48 last week. The math is complicated because I now have a 5 short: 10 long ratio against a put #fuzzy but looks like anything above 99.04 and I break even or make money. If we drop I can always sell 5 again to take the ratio back to 1:1. Since doing that I am up $1635 on the credit spread part this morning.
I will be doing this with any breached credit spread going forward based on the TT research that showed violated credit spreads rarely return to the original range. As long as there is more than a week left to expiration. If inside that would roll first out to 21 DTE or so and then back ratio.
EXPE STO 10 of the 23 DTE 118/120 CCS for 0.40 against a 20 contract put #fuzzy.
Will start some #spycraft on Monday once my LNG and XBI cc are assigned.
SPX 1-dte closed
#SPX1dte Exited short puts for .05, but had to pay .55 to exit call side. Condors sold for 1.20 yesterday.

LABU
#CoveredCalls
STO Feb 15 60 cc @ 1.30 with shares selling at 45.65. Time to start working off -15 pt assignment, returning from PSP sun break, yuk, only a couple days in 70’s. Flight last night w/minor mechanical, TSA’s in good spirits!
#earnings #shortstraddle BBBY Sold Jan….
#earnings #shortstraddle BBBY
Sold Jan. 18, 12 straddle for 2.02, profitable just outside max 1 day moves.
WYNN
#CoveredCalls #IRA – Rolling….
Rolled WYNN JAN 11 2019 110.0 Call to FEB 15 2019 120.0 Call @ even
Slow week…
Working most of the week so not much going on here. Waiting for some earnings dates to get confirmed before selling much more.
BBBY earnings analysis
#Earnings $BBBY reports tonight. Below are details on earnings one-day moves over the last 12 quarters.
Sept. 26, 2018 AC -20.99% Biggest DOWN
June 27, 2018 AC -3.81%
April 11, 2018 AC -19.95%
Dec. 20, 2017 AC -12.49%
Sept. 19, 2017 AC -15.87%
June 22, 2017 AC -12.12%
April 5, 2017 AC 3.38% Biggest UP
Dec. 21, 2016 AC -9.17%
Sept. 21, 2016 AC 0.74%
June 22, 2016 AC 1.50%
April 6, 2016 AC 0.32%
Jan. 7, 2016 AC 0.27%
Avg (+ or -) 8.38%
Bias -7.35%, strong negative bias on earnings.
With stock at 12.00 the data suggests these ranges:
Based on current IV (expected move per TOS): 10.12 to 13.88
Based on AVERAGE move over last 12 quarters: 10.99 to 13.01
Based on MAXIMUM move over last 12 Q’s (21.0%%): 9.48 to 14.52
Open for requests on other symbols.
#earnings BBBY Jeff-do you have…
#earnings BBBY
Jeff-do you have BBBY earnings data? thanks
#shortputs #closing AXDX Nov. 13…
#shortputs #closing AXDX
Nov. 13 sold a Dec. 12.50 put for .65, Dec. 14 rolled it to January, Dec. 31 rolled it to February, closed today and made 95.95.
Still have 100 shares assigned in Oct. at 30, cost basis down to 18.
TQQQ calls sold
#LongLEAPs #SyntheticCoveredCalls
Sold $TQQQ Jan 11th 42.5 calls for 1.45. A roll from this week’s calls that were stopped out.
Fed minutes
Heads up… Fed minutes released today at 2pm ET. Potential market mover.

Markets
#shortstock #coveredputs HIG Sold short…
#shortstock #coveredputs #shortcallspreads HIG SPY
HIG Sold short 100 shares at 43.26
HIG Sold Jan. 18, 42 put for .33
SPY sold Feb. 15, 270/280 call spread for .94
SPX 1-dte
#SPX1dte Sold $SPX Jan 9th 2485/2505/2620/2640 condors for 1.20.
SQ calls sold
#LongLEAPs #SyntheticCoveredCalls
Sold to Open $SQ Jan 18th 66 calls for 1.35. Replace the Jan 4th calls I stopped out of yesterday.
#ironcondor HD Modified TastTrade idea,…
#ironcondor HD
Modified TastyTrade idea, sold Feb. 15, 155/160/190/195 for 1.02
#coveredcallcampaign AAPL #shortstrangles WLL AAPL…
#coveredcallcampaign AAPL MRO DDD #shortstrangles WLL
AAPL Sold Jan. 18, 160 call for .38
MRO rolled Jan. 18, 15 call to Feb. 15 for .45
DDD sold Jan. 18, 11 call for .34
WLL Dec. 4, sold Jan. 18, 26/38 strangle for 1.68, closed today for 1.08.
SPX 1-dte IC
Sold SPX Jan9 2635/2640 BeCS @ .25 x5. Will buy bull put spread later today when conditions look a little better to do so.
Sold SPX Jan9 2495/2490 BuPS @ .30 x5 to complete the IC.
Defense plan: use @hcgdavis tactic to buy back 2 or 3 of the shorts to create a ratio should either of these credit spreads get in trouble.
Calls stopped
#LongLEAPs #SyntheticCoveredCalls First time I’ve had to do this in weeks. Both strikes breached so I exited on pull back and will wait for spikes higher to roll.
BTC $SQ Jan 11th 61 calls for 1.65. Sold for 1.20 on Friday.
BTC $TQQQ Jan 11th 40 calls for 1.30. Sold for .85 on Friday.
UNG
#LongPuts #LEAPS -I’m a little disappointed in this one. It could’ve been a really good one but nat gas just imploded way faster than I thought was possible and my ratio was a little high on the put sales. On the bright side, between this and BOIL the Nov spike worked out ok.
Bought to Close UNG FEB 15 2019 29.0 Puts
Sold to Close UNG JAN 17 2020 28.0 Puts
All said and done it’s a .50 winner on a 15 lot…
WTW
#LongCalls #LEAPS – Stock could be going to zero 🙂
Bought to Close WTW JAN 11 2019 46.0 Calls @ .05 (sold for .70)
SPX 1-dte closed
#SPX1dte Earlier, closed $SPX Jan 7th shorts, puts for .05 and calls for .15. Condors sold Friday for 1.10
OLED
#ShortCalls – I’ll be out most of the next few days but did get one fill this morning…
Bought to Close OLED JAN 11 2019 100.0 Calls @ .05 (sold for 1.75)
SPX Credit Spread
STO 2/28 2140×2120
BTO 2/28 1200p
1.3 credit.
#spycraft version 3.2 Ok guys…
#spycraft version 3.2
Ok guys (and gals). I did a bunch of research over the last 2 weeks. With the market volatility I wanted to restart these trades and also want the consistency back. My trading has been all over the map the last 14 weeks. I used to belong to a service that used this tactic exclusively but I dropped out after I thought I knew everything there was (wrong I still could not contain the max loss trades). Anyway, I was able to find results and trades going back to 11/14/14 to present. I had most from the service up until last year but was able to find a track record up to just a few weeks ago. I will spare you the details but the numbers are still impressive and include some wicked volatility spikes. I looked at every trade and if I had questions about the close used thinkback to see where prices were for opening and closing. Yes it was a lot of work but worth it.
Trades were placed every Friday during that time.
A total of 6 losing trades over that time but only 3 went to full loss. You can probably guess the dates (2 in August and 1 in December of 2015). Surprisingly Feb. 2018 did not result in a loss. The other losses were shut down early and I think that is what saved the service from having major losses. There were a few that were closed early either for a scratch or only a few pennies within the opening price.
Over that time the trades made 563.2% total returns.
78% annualized returns.
93.9% win rate, expected win rate was only 84% confirming what a lot of TT has proven. There is your “edge”.
So anyway I am restarting these in 3 smaller accounts, all under $7500 and one with only $1500 with the goal of doubling the account yearly.This most recent year they had 299% returns. I plan to manage it very mechanically but there are other options for those that want to do it differently.
Here are the rules and some guidelines to be consistent and prevent the big blow outs that can happen with credit spreads/Iron condors.
1. This is designed for SPY but would also work on SPX or /ES for those with larger accounts. However other tickers may even be better. I am sure IWM, QQQ, DIA would all work. I will use SPY.
2. 1 trade opened each week, usually Friday but since I am off Thursdays that will be my trade day.
3. Most of the time open an IC with short strike deltas around 16. However may leg in when the market is whippy.
4. DTE 21-56 but most often will be 3 weeks to 5 weeks. I plan on starting 21 DTE.
5. Run it as a ladder, each week will add a new rung.
6. 2-5 points between strikes. Need to have a little room there for adjustments but will also bring in more credit but keep the risk reasonable. The service mostly used 3-4 wide on the strikes. I will use 3 at first to not use up too much margin.
7. Keep enough cash available to make adjustments or close early. You will probably need enough cash to either buy back half of your shorts or add half as many long options between the strikes.
8. Delta neutral hedge when needed to create a back ratio. I personally will be using 2:1 but a ratio of 3:1 or even 4:1 may work depending on how early you catch it.
9. Expiring options that look like they really will close OTM will be allowed to expire thereby saving commissions. However, a lot of the time they will be closed early if there is enough profit.
10. Options that are close to being ITM will be rolled to new series.
11. There are probably 3 ways to control risk when the short option goes ITM but I am using a hard rule for this now. As soon as the short strike is violated I will do 1 of 3 things. This based on some TT research that showed violated credit spreads return to their range less than 2-20% of the time. If the strike is violated, you are probably in a trending/directional market at that point. These also depend on how much time to expiration. If there are a few weeks will go directional. If in expiration week will just shut it down.
A: buy back half of the short options creating a 2:1 back ratio. Then if we keep moving, you make some money from
the directional kick.
B: If I don’t have enough cash for that then I will just close the violated spread. In TOS you can probably set a
conditional order that would get you out for a 1.5-2 x the credit.
C: Add some long options between the strikes in same ratio as A, 2:1. This may be cheaper than buying back
the short strikes. Since SPY has 0.5 strikes would go 1.5 strikes from the short on a 3 point spread.
That’s it. We know this works, just have to control the losses and I think that is the key to success with this tactic. Let’s see how it works again with the hard rules for adjusting.
AMAT
#LongCalls #LEAPS – Booking full position double sales and replacing with a tighter 4×10 ratio…
Bought to Close AMAT JAN 11 2019 37.0 Calls @ .05 (sold for .32)
Bought to Close AMAT JAN 18 2019 39.0 Calls @ .07 (sold for .31)
Sold AMAT FEB 1 2019 36.0 Calls @ .65
#ironcondor DIA Sold Feb. 15,…
#ironcondor DIA #shortstrangles SQ
DIA Sold Feb. 15, 215/220/250/255 for 1.36
SQ sold Feb. 15, 45/75 strangle for 1.48
#coveredputs PM Sold Jan. 18,…
#coveredputs PM #coveredcalls WYNN
PM Sold Jan. 18, 66 put for .56, woulda, coulda, shoulda sold it yesterday
WYNN Sold Jan. 18, 120 call for .60
SPX 1-dte
#SPX1dte Sold to Open $SPX Jan 7th 2440/2460-2590/2610 condors for 1.10.
#shortstrangles #closing GM MS Closed…
#shortstrangles #closing GM MS
Closed two Jan. 18 strangles for very small change after today’s rally, both were losers yesterday.
Calling again
#LongLEAPs #SyntheticCoveredCalls
Sold $TQQQ Jan 11th 40 calls for .85
Sold $SQ Jan 11th 61 calls for 1.20.

Closing FB
Bought to close $FB Jan 18 125/120 BuPS @ .36. Sold for 1.15 on 12/31.
Closing BA
Bought to close $BA Jan 18 290/280 BuPS @ .43. Sold for 2.20 on 12/27.

Buh Bye NFLX #CostBasisReduction Winner…
Buh Bye NFLX #CostBasisReduction Winner
My NFLX saga ends today…with a bottle of champagne after the close. After the last earnings report when NFLX soared, I got the “great” idea to buy 100 shares at $358 and sell DITM calls for a guaranteed win. Within days there was a massive crash. I took inspiration from seeing @fuzzballl accomplish significant cost basis reduction with patience and perseverance. I vowed I would stick with this until it was profitable. Every single week I sold calls, and bought put butterflies (BWB debit flies). Most of the time they brought in nice credits, there were a few weeks that were debit rolls (debit rolls would step back cost basis those weeks), but I steadily took Cost Basis from $358 to $272. Today I was able to close out the full position for a net $1547 gain.
SPX Feb condor
#SPX1dte Sold $SPX Feb 2250/2270-2730/2750 condors for 3.00. Will close at or near 50%, or 1.50.
Econ calendar for week of 1/7/19
Fed minutes, Wednesday at 2pm ET.


Link to calendar: https://us.econoday.com/byweek.asp?day=7&month=1&year=2019&cust=us&lid=0
EWW REGN TNA UVXY WYNN
#LongCalls #LongPuts #LEAPS – Rolling some and booking some….
EWW: Precautionary…
Bought to Close EWW JAN 4 2019 42.5 Calls @ .15 (sold for .36)
REGN: Selling against ITM bull put spreads…
Rolled REGN JAN 4 2019 385.0 Call to FEB 1 2019 405.0 Call @ .09 credit (should be prior to earnings)
TNA: Booking over sales early just in case the rally continues…
Bought to Close TNA JAN 11 2019 50.0 Calls @ .26 (sold for .90)
Bought to Close TNA JAN 11 2019 55.0 Calls @ .03 (sold for .82)
UVXY: Rolling short puts…long puts finally starting to help. Added a couple BeCS also…
Rolled UVXY JAN 4 2019 80.0 Puts to FEB 1 2019 72.5 Puts @ .65 credit
Rolled UVXY JAN 4 2019 81.0 Puts to FEB 15 2019 70.0 Puts @ .26 credit
Sold UVXY JAN 18 2019 80.0/85.0 Bear Call Spreads @ 1.17
WYNN: Booking over sales early just in case the rally continues…
Bought to Close WYNN JAN 11 2019 114.0/124.0 Bear Call Spreads @ .85 (sold for 1.05)
TQQQ
#CoveredCalls – Adding one here. This is against some of my lower basis stock…
Sold TQQQ FEB 15 2019 44.0 Call @ 1.35
SPX 1-dte closed
#SPX1dte SPX hit my upside stop (expected move breached the 2520 short calls), so I exited on the pull back.
BTC $SPX Jan 4th 2520/2540 call spreads for 1.70. Condors sold yesterday for 1.25. Puts will expire, or close for .05.
I’ll be selling another 1-dte for Monday expiration. I’m looking for longer term roll options to replace today’s stop.
Credit spread tweaks
EOG STO the 21 DTE 97/98 ccs for 0.23. Cb now 14.41 against a 120/120 and 125/126 put #fuzzy
EXPE STO the 21 DTE 117/118 ccs for 0.20 credit. Cb now 9.43 against a 110/110 put #fuzzy.
It rained over the weekend and my family was busy so I watched a bunch of tasty trade re-runs. 2 things I forgot about. They did a section on defined risk and looked at the number of times tested credit spread returned back to the level you placed the spread. It was less than 2:10 times, actually I think as they looked across multiple occurrences and it was much lower around 2%. So gave me an idea for credit spreads and #spycraft which I will start up again next week after some CC are called away.
I will be very mechanical in adjusting credit spreads now. As soon as the short strike is breached, I will delta hedge it to neutral and create a back spread. Odds improve that if it is breached will not return to that level so at that point you have a directional trade and might as well take advantage if it.
What this means is that if the short strike is breached, I will buy back half the # of shorts calls/puts as the original credit spread thereby creating a 2:1 back ratio. Then if we keep moving in that direction you get the boost from the directional kick.
Probably best to set these up 21-45 DTE so you have some room. A weekly probably would not work as well once ratioed because of the gamma effects close to expiration.
December Jobs Report
#Jobs Much higher than expected.
+312,000 non-farm payroll jobs, vs. 176K expected
Unemployment at 3.9%, up 0.2%
U6 unemployment at 7.6%, unchanged
Wages up 0.4%, 3.2% year over year
Labor force participation 63.1%, up by 0.2
November revised up from 155k to 176k
October revised up from 237K to 274k
Reading posts a lot of…
Reading posts a lot of us are under water on a lot of tickers. Out on a bike ride I had a thought. Obviously selling below the cost basis a snap back rally you then lock in your losses if assigned.
I have been saying it for a while but have yet to do it, sell ATM call credit spreads. Bring in a little income, if the market rockets upward you are long stock, short an equal # of calls, but then have the same number of calls long or any ratio you choose. No cap to the upside.
Personally I am going to do this on my TQQQ trades with the next roll. Roll down right to ATM and then be long net calls for free.
Probably not the best to do these with weeklies, I would go out 30-90 days to give them some room. Then if you want back in the stock, let your long calls exercise.
As for my losing put #fuzzy, duh on my part, I should be selling CCS spreads all the way down. We reverse and I will back ratio them. The problem is I always do it too late. From now on if I sell a delta 20-30 and it reaches delta 30-50, that is the point I will back ratio and hopefully get a directional kick. If nothing else at least reduce the max loss.
Thoughts? Other ideas?
SPX 1-dte
#SPX1dte Sold $SPX Jan 4th 2345/2365-2520/2540 for 1.25.
Fully hedged on SSO, TNA, TQQQ, and TNA
Lightened up the hedges on my shares earlier this week so they could run. Now I’m back to weekly ATM short calls, put flies and WOTM puts. Who woke up the bear?
#shortstock PM Sold 100 shares…
#shortstock PM
Sold 100 shares short for 66.95
Also in the short world, DENN up another .30 today arrgghhh
Lots of trading and work,…
Lots of trading and work, not much profit. The #fuzzy trades hold up well but since I am so far out in time and so far ITM on some of these now, not much income or fast theta decay. Had I known we would be in a full bear I would have unhinged them and would be collecting profits now.
#fuzzy
EOG 110/110 puts are now way ITM. Market makers are being greedy. I have an order in to roll the 29 DTE out to 43 for 0.45 credit but no one will take it. If I can’t roll it will reset or shut the entire thing down for about a 6 point loss as it gets closer to expiration. Hoping for at least a little bump in oil prices. cb 14.64
EXPE 125/126 and 120/120 rolled the 15 and 22 DTE out to 36 and 43 DTE for a total of 2.1 in credits. Cb now 9.63.
GILD 70/70 nice bump today. Cb 8.48 and will roll in a few weeks.
MU 35/35 cb 14.80. Getting dragged down further into the black hole by AAPL.
WDC 40/40 cb 19.11 same as MU.
XBI 80/80 cb 13.97
LNG 50/65 cb at 14.54
GILD lot 2 67.5/69 cb 8.9
Most of these are out 15-22 days before further rolling.
#pietrades
TQQQ 50 cc at 57.60 cb. Will either roll to a leap in 2 weeks or hope for rebound. IRA so I can sit on it but would like to be generating some income.
TQQQ lot 2 50 cc 58.10. Same story.
LNG 61 cc expires next week, cb 57.7 and if expires ITM will be first real winning trade in 13 weeks.
LNG lot 2 61 CC cb 58.53 sam as above.
#lizardpies
SQ 55.5/55.5/56.5 straddle expires tomorrow rolled down to strangle 54.5/55.5/56.5 for 0.49 credit. Total credit now 2.04 with cb of 53.46 if assigned and no risk to upside.
I really think the jade lizard will be an excellent tweak to the #pietrades and possibly increase returns another 10% annualized. As I unwind some of these other trades will be putting more of these on.
I also need to be much better at directional trading!!!!
As I have said before, the income will not keep up with the drops, as much as the market is a 50-50 proposition, the more I trade the more I realize being right on directional makes a huge difference to the success of a trade and profits in general.
WTW
#LongCalls #LEAPS – 105 down to 37 and I still plan on making money on this…LOL. I sure know how to pick ’em!
Sold WTW JAN 25 2019 43.5 Calls @ .60
PVTL covered calls
#CoveredCalls Sold $PVTL Jan 18th 17 calls for .50.
Market Tide indicator today…
#Scalping -Been in and out today so no trade (fuzzy skeered…LOL) but the indicator seems to be working nicely in the chop.

LABU
BTC January 18, 63 calls at .05 and STO January 18, 40/45 calls spread for a credit of .52 cents. It is a good thing that I have 2 years to go on these.
#coveredcalls #firsttrade of 2019 AAPL…
#coveredcalls #firsttrade of 2019 AAPL
bought to close Jan. 4, 160 call for .02 yipee
Calls closed (again)
If I was only selling calls and didn’t have #LongLEAPs, this would be a brilliant strategy!
BTC $TQQQ Jan 4th 39.5 calls for .05. Sold for .74 on Friday.
BTC $SQ Jan 4th 59 calls for .05. Sold for .79 on Friday.
OLED
#ShortCalls – Stops set on previous call sales so adding a half position here prior to earnings. See if I can talk it into a small recovery…
Sold OLED JAN 25 2019 97.5 Calls @ 1.20
CELG
I rolled my January 18, 2019, 95 calls out to the January 2020, 95 calls for a credit of 2.80
CELG
Bristol-Myers to buy Celgene in a $74 billion deal; Celgene shares surge…
https://www.cnbc.com/2019/01/03/bristol-myers-to-buy-celgene-in-a-74-billion-deal.html
Market tide
@hcgdavis @fuzzballl
Thanks for recommending this indicator and for going to bat to get us a discount. The indie has paid for itself a few times over already.
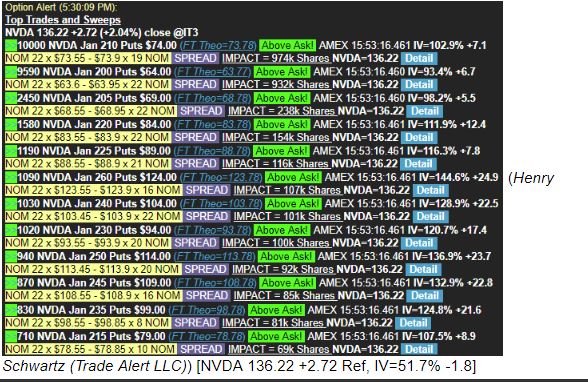
Dodeka-Stupid on NVDA
Here’s a note that Trade Alert put out tonight:
Market Color NVDA – Interesting 12-leg Nvidia put spread minutes before the close totals nearly quarter-billion dollars premium. Over 31K deep puts traded in NVDA at 3:53PM ET today in an odd spread that involved 12 deep-in-the-money puts expiring Jan 18th. Stock was $136.22 at the time, and the package consisted of offer-side blocks in the 200 to 260 strike puts, priced from $64 to $124. Weirdly, size of each block is very near the open-interest of each contract and the price on each block was a whole dollar figure, 22c over parity, with total premium just under $244M. If the package was a buyer of all legs, the delta is nearly 2.4M shares, or 9% the adv of the stock. With negative AAPL headlines out after the close, NVDA shares are down nearly $4 to $132 which could be a gain near $9M if the spread was a dodeka-stupid.
That turned ugly quickly….
Guess the meeting didn’t go so well….buckle your seat belts.

A TRADE:
ROKU STO 1/4/19 32.5 CALLS @.80 Covered Expires in 2 days.
Alpha Shark Indicator
@MamaCash – Have you used it much? Finally got a chance to watch it for a day and liking the possibilities. Haven’t done anything live yet but the last long signal on the NQ futures finally went short this afternoon after a 240 point run…

#longputs Buy another Jan 02…
#longputs
Buy another Jan 02 2510/2500 BePS for $7.50 while SPX below 2500, 15 minutes to go and looks promising.

